

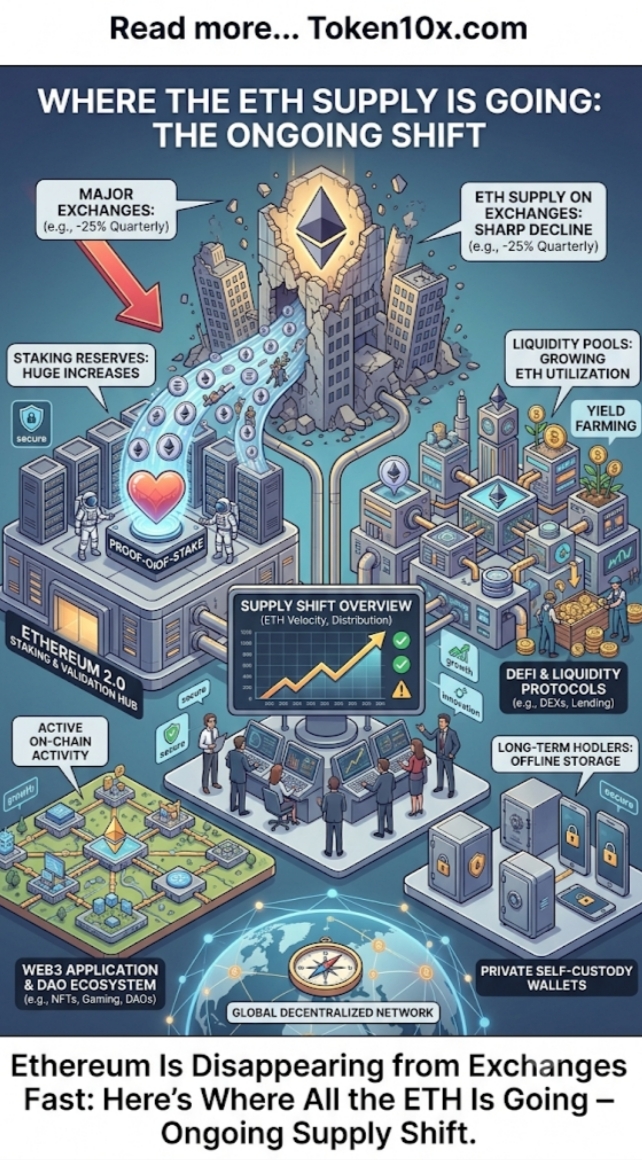
Ethereum continues to see a sustained reduction in the amount of ETH held on centralized exchanges, with balances reaching multi-year or record lows. As of on-chain data from Santiment reported around September 24–25, 2026, only about 3.49% of total ETH supply remains on tracked trading platforms, after another 1.16% of supply moved off exchanges since June 1.
The decline still leaves fewer tokens immediately available for trading or selling on order books. Primary destinations for the withdrawn ETH include staking contracts, decentralized finance protocols, long-term self-custody, and large institutional or treasury holdings. This comparison underscores a structural shift away from exchange liquidity toward yield-generating and longer-term positions.
The Drivers of the Exchange Outflows
The key factor remains the growing utility of ETH beyond simple trading. Roughly 35% of Ethereum’s total supply is estimated to be staked, locking coins into the proof-of-stake consensus mechanism to earn rewards and secure the network. Significant additional amounts are deployed in DeFi, where total value locked on Ethereum stands near $53 billion, providing lending, liquidity provision, and other yield opportunities.
This stacks with accumulation by long-term holders and corporate or treasury entities. Large holders such as BitMine have reported staking multimillion-ETH positions, further removing coins from immediate circulation. Exchange balances had already been trending lower through the summer, and the continued outflows reflect holders preferring on-chain productivity or cold storage over keeping assets on trading venues. Only sustained multi-month reductions of this scale typically push the percentage of supply on exchanges to such low levels; shorter-term fluctuations are more common.
It is essential to distinguish: the drop to 3.49% of supply on exchanges measures the decline in readily tradable balances on tracked platforms, whereas the destinations—staking, DeFi, and self-custody—represent where that ETH is now held or utilized. The movement is mostly a reallocation of existing supply linked to yield opportunities and holder conviction rather than new issuance or destruction.
Market Impact and Broader Context
As ETH leaves exchanges at an accelerated pace, the shrinking liquid float advances discussions of potential supply constraints if demand increases. Lower exchange balances grow the possibility that even moderate buying pressure could have a more pronounced price effect, though reduced supply alone does not guarantee upward movement. Market participants continue to monitor staking queues, DeFi TVL, institutional treasury reports, and residual exchange reserves for confirmation of the trend’s persistence.
This sustained outflow pattern fuels analysis of Ethereum’s evolving economic model, the appeal of native staking yields, the role of DeFi in locking capital, and the growing presence of large long-term holders. Advocates of the scarcity narrative highlight the record-low exchange percentage and the roughly 35% staked share. More cautious observers note that coins in staking or DeFi can still re-enter circulation over time and that price ultimately depends on net demand.
On-chain analysts emphasize that the combination of staking, DeFi deployment, and treasury accumulation has structurally reduced the share of ETH sitting idle on exchanges. The September data offer insight into how Ethereum’s supply is being redistributed across productive on-chain uses and longer-term custody.
As further exchange-balance, staking, and DeFi metrics emerge, the durability of this reduced liquid supply will become clearer.
This analysis draws from Santiment on-chain data and related market reporting for precision. Exchange supply figures depend on the set of tracked addresses and analytical methodologies, and they remain subject to ongoing blockchain activity.