

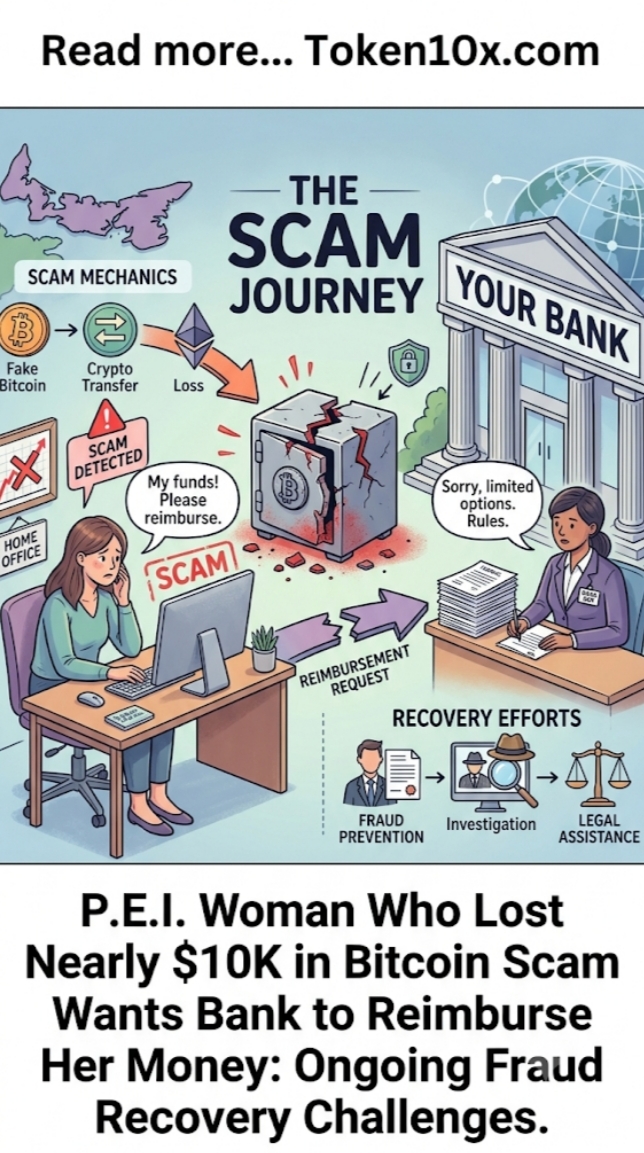
A resident of Prince Edward Island continues to seek reimbursement after losing nearly $10,000 in a bitcoin-related scam, highlighting persistent difficulties victims face when funds are transferred through financial institutions. As of recent local reporting, the woman has approached her bank requesting recovery of the money she lost after being directed to convert cash into cryptocurrency as part of the fraud.
The case still reflects a common pattern in which scammers instruct victims to withdraw funds from their bank accounts and deposit them into bitcoin ATMs or send cryptocurrency, after which recovery becomes highly limited. Banks frequently decline reimbursement when the customer authorized the transactions, even if they were induced by deception. This comparison underscores the gap between traditional fraud protections and the irreversible nature of many crypto transfers.
The Drivers of the Incident and Reimbursement Request
The key factor remains the mechanics of social-engineering scams that exploit urgency and authority. In typical scenarios matching this description, fraudsters pose as officials or trusted parties, pressure the victim to act quickly, and direct them to liquidate bank funds into bitcoin via ATMs or peer-to-peer transfers. Once the cryptocurrency is sent, it is rapidly moved through multiple wallets, making tracing and recovery difficult.
This stacks with standard bank policies that distinguish between unauthorized account access (which may qualify for reimbursement) and authorized transactions resulting from scams. When a customer personally approves withdrawals or transfers—often while remaining on the phone with the scammer—financial institutions commonly classify the loss as the customer’s responsibility. Only limited circumstances, such as clear evidence of bank error or specific regulatory protections, typically lead to reimbursement; most pure scam losses do not.
It is essential to distinguish: the nearly $10,000 figure represents the amount the victim reports losing to the scam, whereas the bank’s position concerns whether the transactions meet its criteria for recoverable fraud. The situation is mostly a consumer-protection and recovery challenge linked to the intersection of traditional banking and irreversible digital-asset transfers.
Impact and Broader Context
As cryptocurrency scams continue to target Canadians, individual cases like this one on Prince Edward Island advance public awareness of the risks and the practical limits of bank reimbursement. Victims who lose funds through bitcoin ATMs or directed crypto purchases often find themselves without recourse once the assets leave the traditional banking system. Police and anti-fraud agencies continue to receive reports of similar schemes involving impersonation and pressure tactics.
This sustained pattern of losses fuels discussions on the need for stronger consumer warnings, potential regulatory measures around crypto ATMs, improved bank protocols for detecting scam-related activity, and education about the finality of cryptocurrency transfers. Advocates for victims highlight the financial and emotional harm caused. Financial institutions emphasize the distinction between unauthorized fraud and customer-authorized payments under duress.
Authorities regularly advise the public never to send money or cryptocurrency in response to unsolicited demands, to verify claims independently, and to report incidents promptly to police and the Canadian Anti-Fraud Centre. The P.E.I. case offers insight into the ongoing challenges ordinary people face when scams successfully bridge traditional banking and digital assets.
As further details of the specific claim or any resolution emerge, the outcome may illustrate broader trends in how Canadian banks and regulators handle crypto-related scam losses.
This analysis draws from the reported circumstances of the case and established patterns in Canadian cryptocurrency scam incidents for precision. Individual outcomes depend on the specific facts, bank policies, and any applicable investigations.