

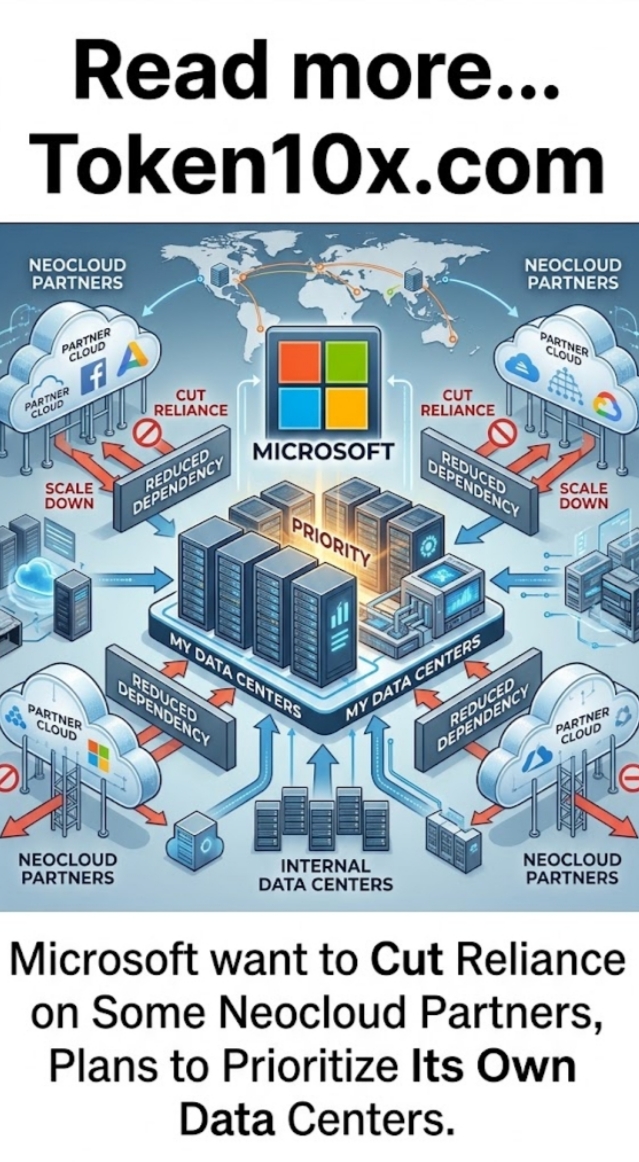
Microsoft is evaluating a reduction in its roster of neocloud partners—specialized providers of GPU capacity for AI workloads—while placing greater emphasis on expanding its own data-center footprint, according to people familiar with the matter. Reports from early November 2026 indicate the company remains in an evaluation phase and has not finalized which relationships to scale back. The shift is not a complete exit from third-party capacity.
Microsoft has worked with multiple neoclouds in recent years, including CoreWeave, Nebius, IREN, Nscale, Lambda, Chronoscale, and Oracle. Specific actions already noted include a decision not to renew a deal with Oracle and pullbacks involving Nscale projects. A company spokesperson has described the overall approach as one of “flexibility and choice,” combining owned data centers, leased facilities, and selective third-party partnerships.
The Drivers of the Current Situation
The primary drivers center on execution challenges and cost predictability in the rapid AI infrastructure buildout. Third-party providers have faced delays in delivering GPU capacity, power-grid connection issues, construction bottlenecks, and equipment shortfalls. Microsoft CFO Amy Hood noted in October that some GPU-related cloud contracts had slipped into the first half of 2027, contributing to adjusted Azure growth expectations. Capital expenditures and finance leases reached $45.2 billion in the most recent reported quarter.
Concrete examples include Microsoft walking away from a roughly $3 billion Nscale data-center project in the UK after power-supply timelines extended into the 2030s, and declining to exercise an option that would have significantly expanded capacity at a Texas Nscale site. Tighter oversight has been applied to projects involving Nebius, IREN, and Nscale. Broader sector pressures—rising borrowing costs, high debt loads among neocloud operators, and regulatory or permitting uncertainties—have heightened scrutiny of external reliance.
Microsoft’s internal priority has shifted toward accelerating its owned infrastructure to better control timelines, costs, and capacity matching to customer demand.
Impact and Broader Context
The reported consolidation raises questions for the neocloud sector, whose stocks have already faced significant pressure amid concerns over leverage and delivery risks. For Microsoft, the move aims to improve predictability in its massive AI and cloud capacity expansion while retaining optionality through remaining key partnerships and leased facilities. It does not signal reduced overall AI investment but rather a preference for greater internal control.
Observers note potential effects on Azure growth pacing if third-party capacity shortfalls persist, interactions with power and construction constraints industry-wide, and competitive positioning relative to other hyperscalers. Sponsors of the strategy emphasize risk management and alignment with demand; critics or affected partners may highlight the challenges of scaling specialized capacity without hyperscaler anchors.
The situation remains fluid. Final decisions on partner reductions, the exact mix of owned versus external capacity, and any further contract adjustments are subject to ongoing internal review and evolving project realities. Market reactions and additional disclosures will clarify the scope.
This analysis draws on reports from CNBC, Bloomberg (via Reuters and other outlets), and related coverage dated November 5–7, 2026, including statements from Microsoft and details of specific project adjustments. The company’s ultimate partner roster and capacity strategy continue to evolve with operational and market conditions.