

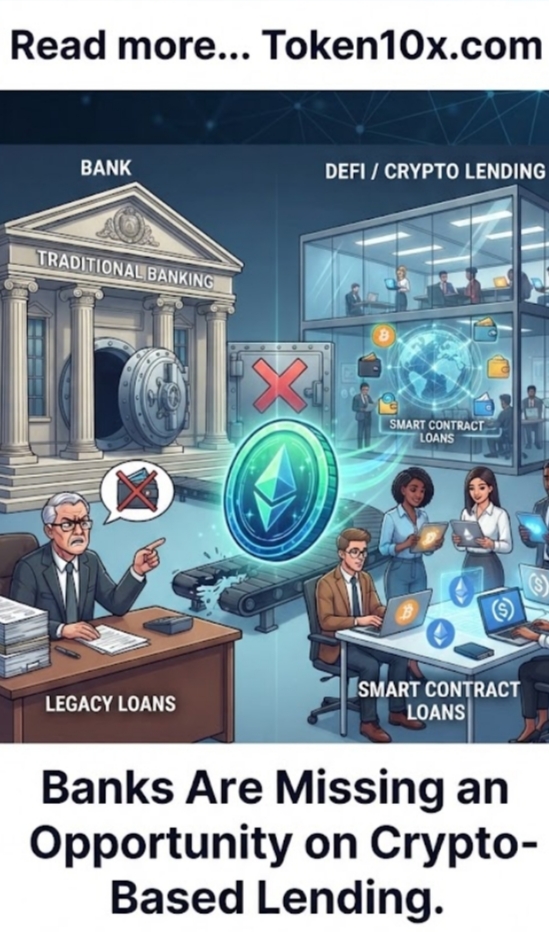
In an opinion published November 18, 2026, in American Banker, BankSocial founder and CEO John Wingate argued that traditional banks and credit unions are largely absent from a rapidly growing crypto-backed lending market that already stands at approximately $68 billion in outstanding loans as of the end of June. Only a tiny fraction of that activity occurs inside regulated depository institutions. Non-bank lenders, including Tether, account for a substantial share of centralized crypto lending, while the remainder operates in decentralized finance protocols governed by smart contracts rather than traditional underwriting or customer relationships.
Wingate contended that as more assets become digital, borrowers will increasingly seek to unlock liquidity against those holdings, and that activity should preferentially occur at banks and credit unions rather than outside the regulated system.
The Drivers of the Current Situation
The main issue is the mismatch between the scale of existing crypto-collateralized lending and the minimal participation of traditional banks and credit unions. Borrowers already post digital assets as collateral at significant volume, yet most of the credit is extended by non-depository entities or automated DeFi protocols that lack the regulatory oversight and relationship infrastructure of banks.
Related factors shaped the opportunity. Crypto lending volumes recovered after earlier industry failures, with centralized non-bank activity and DeFi continuing to intermediate the bulk of loans. Only the reported $68 billion in outstanding crypto-backed loans as of June, the observation that a tiny fraction sits with banks or credit unions, Tether’s large share of non-depository lending, and the argument that this activity should migrate to regulated institutions are verified. Regulatory caution, operational complexity, and historical volatility in crypto markets have constrained bank involvement.
Continued monitoring requires observation of regulatory clarity, pilot programs by banks or credit unions, and shifts in the share of lending captured by depository institutions. Limited public data on exact bank market share forms a narrower path for quantifying the gap. Bank executives, credit-union leaders, fintech platforms focused on digital-asset collateral, and policymakers remain the primary parties tracking residual effects. The situation is a structural opportunity in which regulated lenders have so far captured only a marginal portion of a multi-billion-dollar collateralized credit market.
Impact and Broader Context
Questions about the future role of banks in digital-asset finance keep growing. The low penetration of traditional institutions creates uncertainty about whether regulated lenders will adapt quickly enough to retain customer relationships as crypto holdings expand, while reinforcing concerns that lending activity could remain concentrated in less-regulated venues. It also elevates attention on the competitive pressure from DeFi and specialized crypto lenders. Banking executives, regulators, and digital-asset borrowers continue to assess the implications.
The issue drives debate on the integration of crypto collateral into conventional credit products. It raises questions about the durability of current bank risk frameworks when applied to volatile digital assets, the limits of existing custody and liquidation infrastructure, risks of continued deposit and relationship leakage to non-bank platforms, effects on near-term product development at community banks and credit unions, and competition between fully on-chain lending and hybrid bank-offered solutions. Coverage notes that proponents see an opening for institutions that can combine regulatory compliance with competitive terms.
The November 18 commentary forced renewed focus on the gap between crypto-lending demand and bank participation. The current discussion shows how subsequent product launches, regulatory guidance, or changes in market share will determine the lasting effect.
New bank or credit-union offerings, updated lending-volume data, or supervisory statements will clarify the practical contribution of the opportunity.
This analysis uses the American Banker opinion and contemporaneous market figures on crypto-backed lending. Adoption rates by traditional institutions and the ultimate scale of bank-mediated crypto credit remain subject to regulatory developments, technology readiness, and competitive responses.