

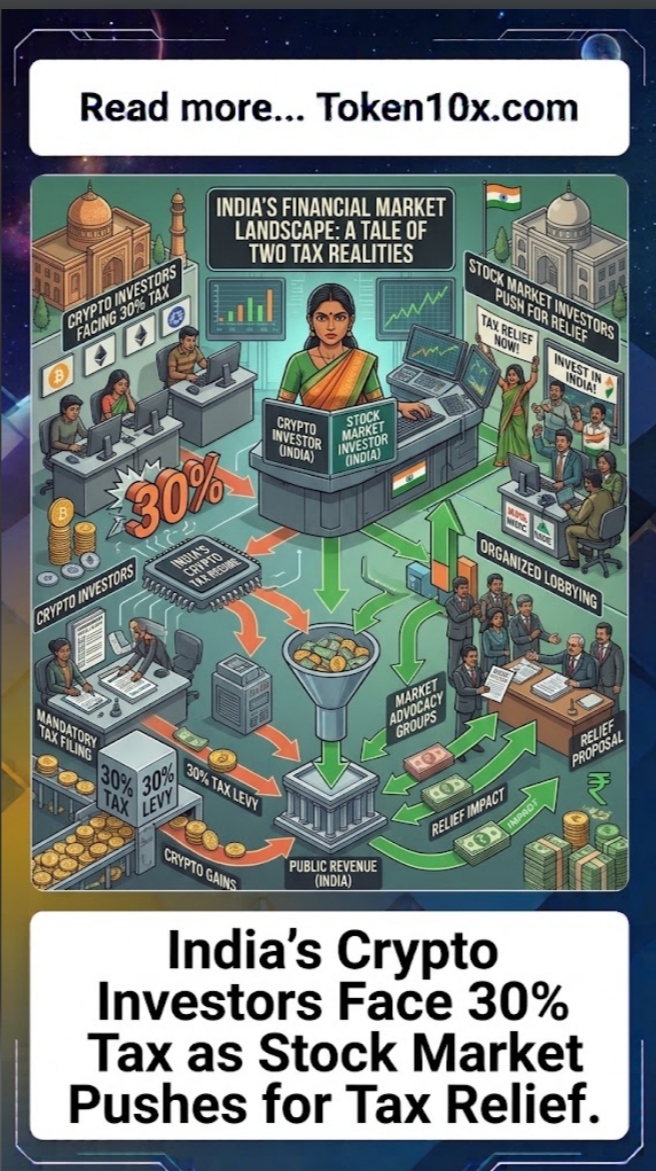
Indian cryptocurrency investors continue to face a flat 30% tax (plus applicable cess, effectively around 31.2%) on gains from virtual digital assets (VDAs) under Section 115BBH of the Income Tax Act, along with a 1% tax deducted at source (TDS) on transactions. The regime, introduced in the 2022 Budget and left unchanged in the 2026 Budget, allows deduction only of the cost of acquisition and prohibits the set-off or carry-forward of losses against other gains or income.
In contrast, equity market participants are pressing for tax relief amid weak market conditions and foreign outflows in 2026. Reports indicate that the Securities and Exchange Board of India (SEBI) and industry voices have proposed concessions for domestic mutual fund and foreign investors to improve post-tax returns. Equity taxation differentiates between short-term and long-term capital gains (with long-term rates substantially lower than 30% and loss set-off/carry-forward permitted for up to eight years), highlighting a clear disparity with the crypto framework.
The Drivers of the Current Situation
The main issue is the persistent gap between the rigid 30% flat tax and 1% TDS applied to crypto gains and the more flexible, lower-rate structure available for equities, at a time when stock market stakeholders are actively seeking further relief. Confirmed elements include the unchanged VDA tax rules through Budget 2026, the inability of crypto investors to offset losses, the 1% TDS mechanism, equity’s holding-period-based rates and loss provisions, and recent calls from the equity side for tax and transaction-cost reductions to support market participation. These differences have drawn attention to the comparative treatment of the two asset classes.
Any future policy statements, Budget updates, or regulatory proposals will determine whether the disparity narrows.
Impact and Broader Context
The dual regime underscores differing policy approaches to traditional equities versus digital assets. It raises questions about the competitive position of India’s crypto market (with reports of significant trading activity shifting offshore), the fairness of taxing gross gains without loss offsets, the effect on domestic investor participation and capital formation, the rationale for treating VDAs more stringently than listed securities, and the potential for future alignment or continued divergence. Coverage distinguishes between the established, unchanged crypto tax framework and the active advocacy for equity relief, noting that crypto industry requests for rate reductions or loss set-off have so far been unsuccessful.
Further developments in tax policy, SEBI recommendations, or market performance data will clarify the longer-term implications for both investor groups.
This analysis draws from the Income Tax Act provisions on VDAs, Budget 2026 outcomes, contemporaneous reporting on equity tax relief demands, and related market commentary. Exact policy changes, if any, and their implementation remain subject to official government announcements and legislative updates.