

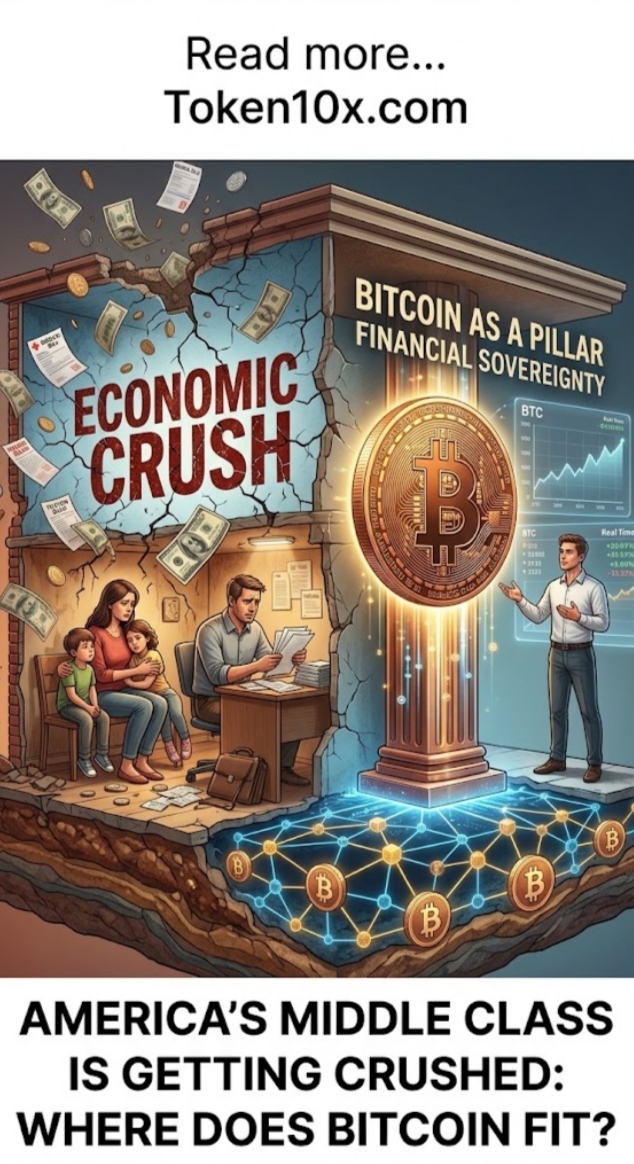
Recent analysis highlights deepening wealth concentration in the United States. As of early October 2026, data referenced by the Kobeissi Letter shows the top 1% of households, roughly 1.4 million, control more than $60 trillion in net worth. Their wealth has risen by over $30 trillion since 2020. The bottom 50% of households hold only a fraction of that total. The discussion centers on whether Bitcoin offers a meaningful response for those outside the asset-owning tier.
Commentators continue framing the divide as one between asset holders and everyone else. They have restricted broader solutions to structural issues such as wages and housing. Cash savings remain exposed to purchasing-power erosion. Analysts rely partly on Federal Reserve wealth distribution figures while routing the conversation through scarce-asset ownership. This highlights the difference between traditional stores of value and more accessible digital alternatives.
The Drivers of the Current Situation
The main issue is the widening gap between asset owners and those relying primarily on wages and cash. The top 1% now hold a record share of U.S. net worth. No single policy change has reversed the trend. Household net worth overall has expanded, yet the gains have been highly uneven.
Policymakers and households have limited immediate tools against the disparity. Some face rising costs for housing, healthcare, and daily expenses. The Kobeissi analysis points to asset ownership as the decisive factor separating those who preserve wealth from those who fall behind. Bitcoin’s fixed supply of 21 million coins is cited as resistant to monetary expansion tied to deficits or policy. Fractional ownership lowers entry barriers compared with real estate or private equity. Only accessibility and scarcity address one specific slice of the problem. Broader economic pressures continue to shape household outcomes.
A complete remedy requires solutions beyond any single asset. Limited individual exposure under persistent structural challenges forms a narrower path. Economists and market observers are actively examining the wealth data. The situation is a distribution challenge tied to asset ownership trends.
Impact and Broader Context
Questions about America’s middle class getting crushed and where Bitcoin fits keep growing. Extreme concentration creates uncertainty for long-term household financial security. It also affects interest in alternative stores of value. Commentators, investors, and policy analysts continue to debate practical responses.
The issue drives debate on wealth preservation strategies. It raises questions about how effectively scarce assets can offset currency debasement, the limits of Bitcoin’s volatility for middle-income holders, risks of treating any single asset as a systemic fix, effects on broader adoption, and competition between traditional assets and digital alternatives. Stakeholders stress that Bitcoin cannot raise real wages, lower housing costs, or redistribute existing wealth. Reports say it can nonetheless give individuals one additional route onto the asset-owning side of the divide in an economy where ownership increasingly determines outcomes.
The recent wealth-distribution analysis forced renewed attention onto accessible scarce assets. The current discussion shows how economic pressures will influence individual allocation choices.
New wealth data, policy measures, or shifts in Bitcoin adoption will clarify its practical role for households navigating the divide.
This analysis uses Kobeissi Letter figures, related economic commentary, and market discussions. Wealth trends and asset outcomes remain subject to ongoing economic conditions and individual circumstances.